Deep dives|Sep 14, 2026|8 min read
Stablecoin Mass Payouts vs Traditional Payout Providers: What Actually Changes
The case for paying people in stablecoins is usually made ideologically: onchain good, banks bad. That framing does not survive contact with a CFO. The real case is operational, and it comes down to three things: how the cost is structured, how long settlement takes, and what happens when a payment fails.
This guide compares the two rails on those terms, for one specific job: paying hundreds or thousands of recipients at once. Not one-off invoices, not consumer remittances, but mass payouts: contributor payments, community rewards, refunds, revenue shares.
It is also an honest comparison. There are payouts where a traditional provider remains the right choice, and pretending otherwise would not help you. We cover those too.
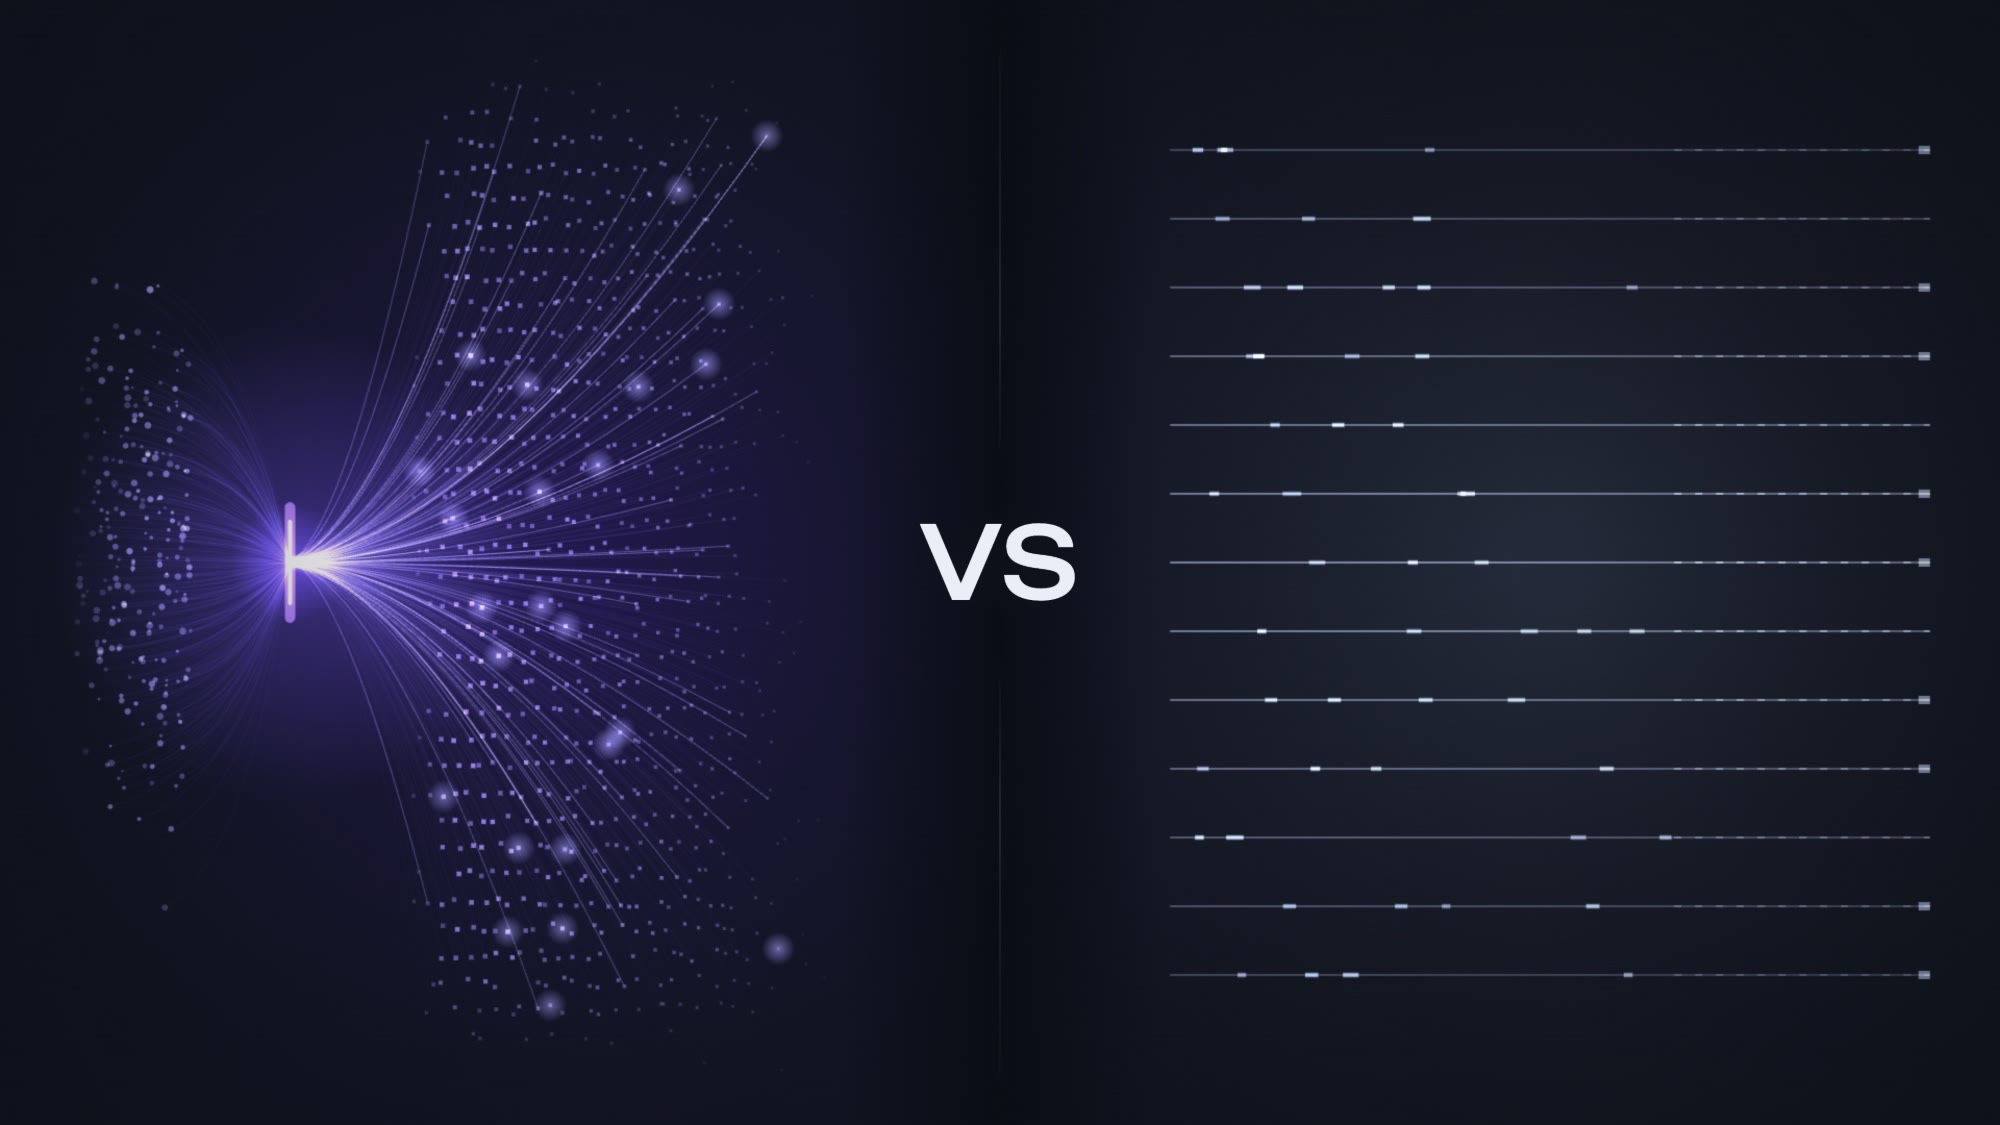
What is a stablecoin mass payout?
A stablecoin mass payout is a batch payment sent onchain to many wallets at once, using a USD-pegged token such as USDC as the payment asset. Instead of instructing a bank or payout provider to execute thousands of individual transfers, the sender funds a single onchain distribution, and each recipient receives or claims their share directly in their wallet.
The stablecoin part matters. It removes the volatility objection that makes most tokens unsuitable for payments: a contributor owed $500 receives $500 of purchasing power, not a token that might be worth $430 by Friday.
How traditional mass payouts price
Whether through banks or a payout platform, the traditional cost structure has the same shape: it scales with the number of payments and the number of corridors.
- A per-payment fee. Every recipient is a separate transaction, each with its own processing cost. Two thousand recipients means two thousand fees.
- An FX margin on cross-border payments. When the payout crosses currencies, a spread is applied to the conversion, priced per corridor. This is often the largest cost and the least visible one.
- Receiving-side costs. Intermediary and beneficiary banks can deduct their own fees along the way, so recipients in some countries receive less than what was sent.
- Failure costs. A wrong IBAN, a closed account, or a compliance hold turns into a bounced payment, an investigation, and sometimes a recall fee. At a few thousand payments per cycle, a small failure rate is a permanent operations workload.
For a sense of what moving money across borders costs on legacy rails, the World Bank's Remittance Prices Worldwide tracker put the global average cost of sending $200 at 6.49% in Q1 2025, with banks averaging 14.55%, the most expensive channel it measures. Business payout platforms price better than consumer remittances, but they price on the same structure: per payment, per corridor, plus FX.
How stablecoin mass payouts price
A stablecoin mass payout through Merkl has a different shape entirely. The cost does not scale with recipients or geography:
- One funding transaction. The sender deposits the total amount once, whatever the size of the recipient list. Gas for one transaction, not two thousand. And the deposit itself is optional: you can keep the funds in your own account, and Merkl draws each payment from it only when the recipient claims.
- A flat 0.5% fee. JSON-based batch distributions on Merkl carry a 0.5% fee, added on top of the distributed amount so recipients receive the full amount. For large distributions, a fixed fee can be arranged. No per-recipient pricing, no corridor pricing.
- No FX spread. A payout in USDC is the same asset for a recipient in Lisbon, Lagos, or Buenos Aires. There is no conversion between the sender and the recipient, so there is no margin on one.
- Claim gas on the recipient side. Each recipient pays the gas for their own claim, typically cents on an L2.
Run the numbers on a concrete case: 2,000 contributors receiving $150 each, across 40 countries, every month. That is $300,000 per cycle. On Merkl, the sender's cost is $1,500 (0.5%) plus the gas of one funding transaction. On traditional rails, even with conservative assumptions of $2 per payment and a 1% FX margin on the converted amounts, the same cycle costs around $7,000: $4,000 in per-payment fees plus $3,000 in FX, before counting the handful of bounced payments. With the pricing many providers actually charge on exotic corridors, the real figure lands higher. The comparison does not get closer as you scale; it gets further apart.
Speed, availability, and failure modes
Cross-border bank payments settle in one to several business days depending on the corridor, inside banking hours, with cutoff times and no weekends. A stablecoin payout is claimable about two hours after the funds are sent, any day, at any hour.
The failure modes differ even more than the speed. A traditional mass payout fails retail: payment by payment, each bounce requiring investigation and manual retry. An onchain distribution like Merkl's has no per-recipient failure mode on the sender's side. Funds sit in the distribution contract until claimed, nothing bounces, and whatever is never claimed can be reallocated by the sender after the distribution ends. Reconciliation is not a report your provider emails you; every distribution and every claim is verifiable on the ledger itself.
This is not theoretical. The largest stablecoin payouts already run this way:
In November 2025, the Stable pre-deposit program was oversubscribed and $634M in USDC had to be returned to depositors. The refund ran through Merkl: $500M was claimed within the first 20 hours, and close to 9,000 wallets were refunded in five days, with the USDC never leaving the Hourglass-managed vault until each claim. Read the case study.
For how this works mechanically, and why the pull model beats push-style multisenders at scale, see our guide to batch token transfers onchain.
Where traditional providers still win
Three situations where the traditional rail remains the better tool:
- Recipients without wallets. If your payees are not crypto-native and you cannot ask them to hold a wallet, a provider that delivers to bank accounts is serving them better, full stop.
- Local currency requirements. Stablecoin rails end at the wallet. If every recipient needs euros or pesos in a bank account, someone has to offramp, and pushing that burden onto recipients is only acceptable when they are equipped for it.
- Domestic, single-currency payouts. A US company paying US contractors in USD through domestic ACH pays little and loses little to FX. The stablecoin advantage is thinnest exactly there.
In practice, many teams end up hybrid: traditional rails for fiat-first payees, stablecoin rails for the international and crypto-native share of the list. The mistake is not choosing one or the other; it is running the international share through per-corridor pricing when the recipients would happily take USDC.
Compliance: what changes and what does not
Moving a payout onchain changes the execution rail, not the obligations. Tax reporting, employment classification, and sanctions screening apply to a stablecoin payout exactly as they apply to a bank transfer, and your counsel should be in the loop either way.
What has changed is the regulatory footing of the asset itself. Dedicated stablecoin frameworks now exist on both sides of the Atlantic, with MiCA in the EU and the GENIUS Act in the US, which is precisely why banks, fintechs, and payment companies have started building on these rails rather than around them.
Running a stablecoin mass payout
On Merkl, the flow takes minutes and requires no code: upload a JSON file of addresses and amounts in Merkl Studio, select the chain and the stablecoin, and fund the distribution in one transaction. Recipients claim from the Merkl App or any interface with the Merkl API integrated.
Two options matter for payouts specifically:
- Custody-preserving wrappers. Instead of prefunding, a wrapper pulls funds from your treasury only when each recipient claims. Nothing leaves your multisig upfront, and unclaimed amounts never leave it at all.
- Private distributions. Private transfers keep the payout invisible in the app and untraceable to the sender, so salaries and individual allocations stay confidential even though the rail is public.
And if your recipients should not have to claim at all, Merkl's Autoclaim service pushes the tokens directly to their wallets on a schedule you define. For non-crypto-native payees, the payout simply arrives.
Ready to send your first stablecoin payout?
Have our team scope it with you, or launch it yourself in Merkl Studio.
FAQs
Are stablecoin mass payouts cheaper than bank transfers?
For cross-border payouts, generally yes. Bank and provider costs scale per payment and per corridor, with FX margins on each conversion; the World Bank measured banks at an average 14.55% cost on cross-border remittances in Q1 2025. A stablecoin mass payout through Merkl costs a flat 0.5% plus one funding transaction, with no FX spread, whatever the recipient count or location.
How fast is a stablecoin mass payout?
Funding takes one transaction. Recipients can claim about two hours later, at any hour and on any day. There are no banking cutoffs, no business-day settlement windows, and no corridor-dependent delays.
Do recipients need a crypto wallet?
Yes. Each recipient claims to their own wallet address, from the Merkl App or any interface with the Merkl API integrated. If a meaningful share of your payees cannot hold a wallet, serve them through traditional rails and route the rest onchain.
Which stablecoin should I use for a mass payout?
USD-pegged stablecoins such as USDC and USDT are the most common choice, for liquidity and recipient familiarity. The practical criteria are the chain your recipients use, the token's liquidity there, and how easily your payees can hold or offramp it.
Is it legal to pay people in stablecoins?
It depends on the jurisdiction and on what the payment is for: contractor payments, employee salaries, and rewards are treated differently in different countries. The rail does not change your tax, labor, or sanctions obligations, so involve counsel the same way you would for any payout program.
Can a mass payout be kept confidential?
Yes. Merkl supports private distributions that do not appear in the app or the API. Individual claims cannot be traced back to the sender, and recipients only see their own allocation, never anyone else's.
Related articles
Deep dives|Sep 9, 2026|11 min read
How to Send Tokens to Thousands of Wallets Onchain: Batch Transfers Explained
How to send tokens or stablecoins to thousands of wallets in one batch transfer: onchain vs traditional rails, push vs pull, fees, and a step-by-step guide with Merkl.
Read more →
Deep dives|May 19, 2026|8 min read
How to Compare DeFi Incentive Platforms: A Decision Framework
Learn how to effectively compare DeFi incentive platforms by understanding the key functions and avoiding common pitfalls in vendor selection.
Read more →
Deep dives|May 6, 2026|9 min read
How to Source Liquidity Providers for Your DeFi Protocol
Learn how DeFi protocols source liquidity providers onchain. Compare network-based outreach vs marketplace discovery, with real data from Merkl's LP marketplace.
Read more →